
On this page
- Keep the record separate from promises about cover
- Start with one ordinary room
- Record facts you can identify later
- Make photographs informative, not decorative
- Use estimates to ask better insurance questions
- Protect the record from the same incident
- Check one recovery task
- Use the inventory safely after a loss
- Maintain it at ordinary life changes
- Finish the first usable version
- Sources
Try listing everything in one kitchen drawer without opening it. Now imagine doing that for an entire home after a serious loss. An inventory gives you a record to work from while dealing with housing, repairs and everyday life. It also gives you a reason to check whether the insurance you have reflects what you own.
You do not need to buy a specialist app before starting. A spreadsheet, a simple document and organised photographs can work. Choose a format another authorised household member can understand. The main requirements are accurate descriptions, traceable evidence and a backup you can recover if the devices and papers at home are lost together.

Full image attribution
433GrossesElektrobuegeleisenGrossagH3a.jpg — HelgeRieder; CC0. Resized and converted to WebP; source: https://commons.wikimedia.org/wiki/File:433GrossesElektrobuegeleisenGrossagH3a.jpg
Keep the record separate from promises about cover
An inventory records possessions. Your insurance contract decides what is covered, where, against which events and subject to which limits. The Association of British Insurers recommends an inventory using replacement values when assessing household contents. It also explains that insurers may ask for ownership and value evidence during a claim.
Read the current schedule and policy wording. Note the insured address, policy period, excesses and relevant limits. Ask about anything unclear before a loss. A photograph of a bicycle in a shed does not establish that the bicycle meets the policy's storage conditions. An item on your list does not automatically become a separately specified item on the insurance.
Buildings and contents are different types of cover. The Financial Ombudsman Service explains the broad distinction between the structure and removable possessions. In a rented home, do not assume the landlord's buildings policy covers your belongings. Use the renters' guide to keep your own contacts separate from the landlord's responsibilities.
Start with one ordinary room
Give each room a clear name and a short code if useful. Photograph the room from a few angles, then open cupboards and drawers for a record of their contents. Keep personal documents, passwords and other unnecessary private details out of the frame. Take close-ups of important items, labels and identifying marks without moving heavy equipment or climbing unsafely.
Do the first room fully enough to test the method. Can you match a photograph to the corresponding list entry? Can you find the receipt? Does someone else understand the description? Fix confusing file names now, before creating hundreds of images. A small completed section is more useful than a complex template that nobody fills in.
Work through less obvious storage spaces later. Hall cupboards, a loft, a shed and boxes under beds can contain costly belongings that never appear in a living-room photograph. Only inspect spaces you can access safely. Note an inaccessible area as unfinished and arrange safe access another day; an inventory is not a reason to balance on furniture or disturb suspect materials.
Record facts you can identify later
| Field | What belongs there |
|---|---|
| Item and owner | A clear description and whose possession it is. |
| Location | The normal room or storage area. |
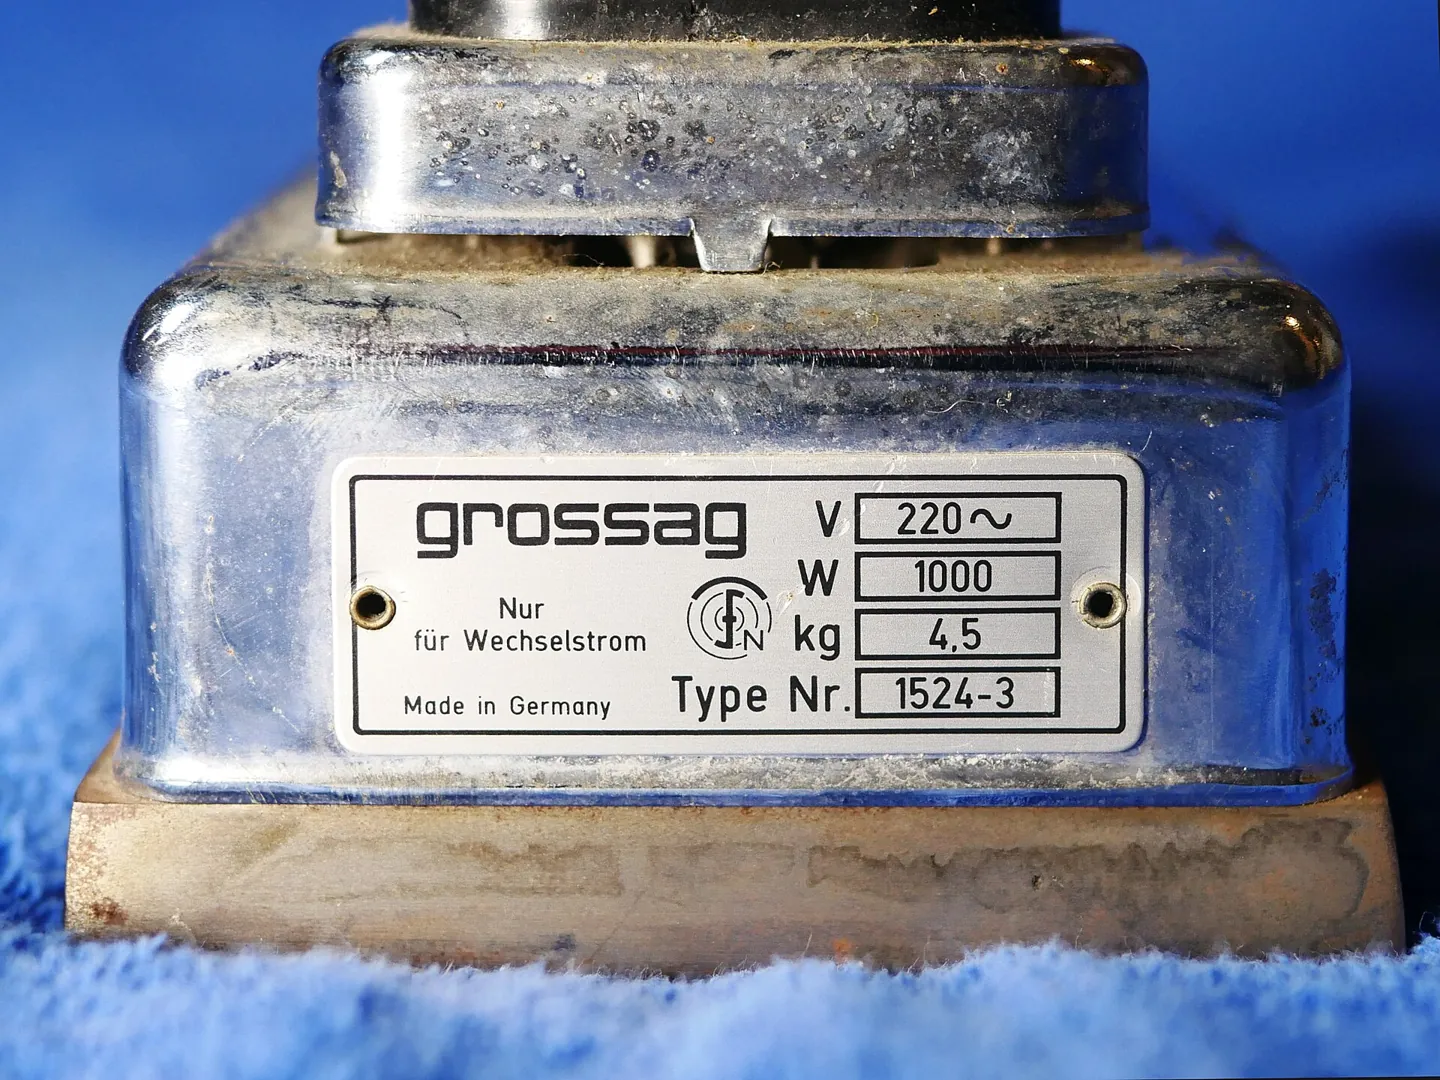
| Identification | Make, model, serial number or distinguishing details where available. |
| Purchase evidence | Receipt, order reference or other evidence, with a file link. |
| Value information | Purchase price if known; a separately dated replacement estimate. |
| Photographs | File names for overview and close-up images. |
| Insurance question | Any need to ask about specification, limits or location of cover. |
Keep uncertainty visible. Use "purchase year uncertain" rather than inventing a date. Mark a replacement figure as an estimate and record how you arrived at it. Do not present a current asking price for a superficially similar item as a professional valuation. Antiques, jewellery, collections and unusual equipment may need a different approach agreed with the insurer.
For ordinary grouped items, decide on a sensible level of detail. You might list a set of dining chairs together while recording a distinctive laptop separately. Avoid a single vague entry called "everything in the bedroom". The record should help reconstruct what was there without requiring an individual photograph of every inexpensive object.
Make photographs informative, not decorative
Check focus and readability as you go. A serial number photographed in glare may be useless later. Include a normal view of the item so the label image can be matched to it. Keep original files where practical and avoid edits that obscure dates, condition or identifying features. Do not stage a photograph to suggest you own something you borrowed.
Use file names that describe the room and item rather than relying on the camera's sequence alone. For example, a room code, item name and date can be enough. Keep the scheme short so you will continue using it. A folder containing only camera numbers can still hold evidence, but finding the right image while discussing a claim is harder.
A video walk-through can supplement photographs, especially for a quick room overview. Speak clearly if narrating, but do not rely on speech as the sole record of a model number. Pause long enough for labels to be readable. Keep the original and check playback on another authorised device. An unreadable file is not improved by the fact that it took an hour to record.

Full image attribution
Manila folder.jpg — allispossible.org.uk; CC BY 2.0. Resized and converted to WebP; source: https://commons.wikimedia.org/wiki/File:Manila_folder.jpg
Use estimates to ask better insurance questions
Replacement cost, purchase price and second-hand sale value are different figures. Label them accordingly. When renewing, use the basis your policy requires and ask the insurer about items you cannot value sensibly. Keep a date beside each estimate so an old figure does not quietly become the current one.
Check the overall contents limit and any single-item or category limits. Ask about valuables, items away from home, equipment used for work, belongings in outbuildings and anything belonging to someone else. The answers depend on the contract. Keep the insurer's reply with the relevant policy year rather than relying on a remembered telephone conversation.
A new purchase is an easy trigger for updating the record. Keep the receipt and make the entry before discarding the packaging, while the model information is easy to find. Gifts and inherited items deserve entries too, with honest notes about available evidence. Ask what evidence the insurer would accept where there is no conventional receipt.
Protect the record from the same incident
A folder beside your computer and a copy on that computer can both be lost in one fire or theft. Keep a protected separate backup, using a cloud service or removable storage appropriate to your circumstances. The National Cyber Security Centre's backup guidance explains separate copies, protection and checking that the data is present.
Think about account access if your usual phone is unavailable. Follow the provider's recovery arrangements and protect sensitive recovery information. Do not put passwords into the inventory itself. Restrict sharing to people who need it, and agree access with other adults whose belongings or private information appear in the files.
Keep a small paper contact sheet rather than a printed catalogue of everything you own in the grab bag. The insurer's claims number, policy reference and a note about where the protected inventory lives may be sufficient for the first call. Your emergency document pack can hold that sheet; detailed records can remain in secure storage.
Check one recovery task
Choose a recent item and try finding its photograph, receipt and list entry from the backup. Open the files rather than merely checking that their names appear. Confirm that a multi-page policy is complete. If someone else will help with a claim, ask them to locate one agreed example using their authorised access.
Write down what failed and simplify the system. Perhaps scans were saved in a different folder, an export omitted attachments or a shared link expired. Solve those problems during ordinary life. The offline document guide covers access when the internet is unavailable, including the limits of storing everything in a cloud account.

Full image attribution
Laptop on desk book stacks (Unsplash).jpg — freddie marriage fredmarriage; CC0. Resized and converted to WebP; source: https://commons.wikimedia.org/wiki/File:Laptop_on_desk_book_stacks_(Unsplash).jpg
Use the inventory safely after a loss
Contact the insurer through a verified number and ask what evidence, inspections and spending authorisation they require. Keep a dated note of conversations, reference numbers and instructions. Distinguish items definitely damaged from those you have not yet been allowed to inspect. Do not turn an early estimate into a claim for losses you have not established.
Only photograph damage when access is safe and permitted. Do not re-enter a fire-damaged or flooded building for receipts or possessions. Ask the insurer before disposing of damaged items when it is safe to retain them, but follow emergency-service or public-health instructions where items are hazardous. Make a note of why urgent disposal was necessary and retain safe evidence if available.
If you disagree with a claim decision, ask the insurer to explain it and use its complaints process. The Financial Ombudsman Service describes the next route for eligible unresolved complaints. Keep the policy, decision and relevant evidence together. The inventory helps explain facts; it cannot by itself settle a dispute about exclusions or policy terms.
Maintain it at ordinary life changes
Review the list at renewal, after moving and after substantial purchases or disposals. Remove sold items from the current list while retaining relevant historic records privately. Check that a changed address or storage arrangement has been discussed with the insurer. A dated annual review is manageable; a promise to document every household movement usually is not.
Use the evacuation security guide for decisions about leaving the property and the fire escape guide for immediate danger. The inventory's greatest practical benefit may be that you know the evidence is elsewhere and can leave without trying to rescue a folder.
Finish the first usable version
- Complete one room with readable overview and identification photographs.
- Match each significant item to available ownership evidence.
- Separate purchase prices from dated replacement estimates.
- Ask the insurer about uncertain limits and retain its answer.
- Make a protected backup away from the original device.
- Open a sample entry from that backup.
- Schedule the next review around renewal or a household change.
Sources
- Association of British Insurers: Contents insurance. Checked 2 November 2026.
- Financial Ombudsman Service: Home and buildings insurance. Checked 2 November 2026.
- National Cyber Security Centre: Backing up your data. Checked 2 November 2026.